What a 5% Market Drawdown Costs at Each FIRE Stage
A 5% market drawdown costs a 15-year accumulator almost nothing, a near-FI saver a few months, and a new retiree a 4.2% withdrawal rate. Price your own.

The S&P 500 fell more than 4% in a single session on November 5, 2026, the Nasdaq 100 lost 5.5%, and emerging markets slid 6% during the November 5 session. By the weekend a broad portfolio was down roughly 5% for the week, and every FIRE forum carried the same question: what did that just do to my plan? Stay the course is the correct advice and a numerically empty answer, because a market drawdown has no single cost. The same 5% week is close to free for a saver with 15 years to go, a bounded and countable number of FI months for someone a year from their number, and a mechanical reset from a 4.0% to a 4.2% withdrawal rate for someone who just retired at 25x. The market printed one number, but your phase set the price.
Stay in the loop.
Get the latest posts and exclusive content delivered to your inbox.
Join 16 readers. No spam. Unsubscribe in one click, anytime.
This piece prices that week three ways with every assumption stated, audits what bonds, international stocks, and cash actually bought on a day when every equity sleeve fell together, and ends with a worksheet you can rerun on your own statement the next time it happens.
Pricing a Market Drawdown in Two Currencies
A percentage headline is the wrong unit of account. "S&P down 4%" tells an accumulator nothing about a FI date and a retiree nothing about a paycheck, which is why the reassurance genre feels so unsatisfying. Price the event in your phase's native currency instead.
- Before your number, the unit is FI months. How many months later does the drop push the day your portfolio reaches 25 times expenses?
- After your number, the unit is withdrawal-rate points. How many tenths did the drop add to your safe withdrawal rate?
Does a stock market drop hurt retirees more than savers? Mechanically, yes, because a retiree has no contributions offsetting the loss, so the same percentage is a bigger event. In realized damage, only sometimes, and the rest of this arithmetic is exactly the line between those two answers.
To keep every figure reproducible, all three phases below use the same household: $40,000 of annual spending, a $1,000,000 FI number (25 times expenses), a portfolio-level drop of 5% matching the November week (the single day was 4%+, the full week closer to 5%), and 5% real returns while accumulating. Swap in your own numbers as you read; the formulas travel.
Phase 1, The Accumulator With 15 Years Left
Run the projection backward. A saver 15 years from the number, contributing at a 50% FIRE savings rate on $80,000 of income, typically holds somewhere around 1.5 to 2 times spending. Call it $65,000, or 1.6x.
A 5% stock market drop takes about $3,300 from that portfolio. In the phase's currency, that is 0.08x, roughly three weeks of contributions. One year of saving adds a full 1.0x, and growth on the existing balance adds roughly another 0.08x. The entire drawdown cancels about a month of your own progress, and the FI date moves by weeks, comfortably inside the noise of your savings rate.
The general formula, which will reappear in every phase:
Damage in multiples = drop × current multiple. Delay in months ≈ 12 × damage ÷ annual progress in multiples.
For this saver: 12 × 0.08 ÷ 1.1 ≈ 0.9 months. That is the sense in which a market drawdown is close to free for a mid-accumulator, and it is why "one year of contributions adds more than a 5% drop subtracts" holds for any portfolio below roughly 10x.
There is even a small silver lining. Your next contributions land at prices 5% lower, buying about 5% more shares per dollar, which is the arithmetic behind dollar cost averaging and the reason buying the dip is a modest expected gain rather than a consolation prize. It is not a lottery ticket; it shifts expected terminal wealth by a fraction of a percent. The honest caveat for this phase is that your real exposure is income, not portfolio value. A drop severe enough to matter is usually a drop that threatens paychecks, which is why the emergency fund, not the drawdown math, is the binding constraint at 1.6x.
Phase 2, One Year From the Number

The same week hits very differently at 24x, or $960,000, with $40,000 left to go.
The 5% drop subtracts 1.2x ($48,000), landing you at 22.8x and widening the gap from 1x to 2.2x. How many months does a market crash add to early retirement at this stage? Divide the damage by your progress rate:
| Annual progress (savings plus growth, in multiples) | Delay at 24x, assuming no recovery |
|---|---|
| 1.2x per year | about 12 months |
| 1.8x per year | about 8 months |
| 2.2x per year | about 7 months |
That is the whole answer to "how much does a market drop delay FIRE": one division. A late-stage saver adding 1.5x to 2x a year faces a single-digit-month delay, roughly half a year, with zero recovery assumed. If you are adding 1.2x, the same event costs about a year, which is the price of a glide path heavy in bonds during the home stretch: the de-risking that cushioned the drop also slows the repair.
The no-recovery assumption is deliberately conservative, because it treats the 5% as permanently gone while your contributions continue. Looking at the history of S&P 500 drawdowns, declines in the 5% range have usually been repaired in weeks to months rather than years. If the index retrace arrives on anything like a normal schedule, the gap reverts toward 1x and the real delay compresses toward weeks. The table above is the ceiling, with the depth and speed of past recoveries pulling the typical outcome well under it.
Two phase-specific traps deserve naming. First, the arithmetic assumes contributions keep flowing; a recession that cuts your income lengthens the delay from the savings side, which is the under-discussed risk of being near-FI in a shaky economy. Second, the drop reprices the one-more-year decision. Quitting now means retiring at 22.8x, a 4.4% withdrawal rate; working the extra seven months buys you back the original 25x. For the first time, the market gave your hesitation a number.
Phase 3, The New Retiree at 25x
Suppose you retired months ago at exactly 25x ($1,000,000), withdrawing $40,000, a clean 4.0%.
The reset is mechanical
What a 5% market drop does to your withdrawal rate at 25x is one division. The portfolio falls to $950,000, or 23.75x, and the withdrawal rate becomes 1 ÷ 23.75 = 4.21%. Unlike the other two phases, nothing repairs it automatically, because there are no contributions. The dollar withdrawal is unchanged; you are simply dividing it by a smaller base.
Paper damage versus realized damage
A 4.2% reading for a few months is a paper reset, and treating it as ruin overstates the event. Sequence of returns risk comes from sustained losses across the first retirement decade, when withdrawals lock in depressed prices and compound the damage. One bad week, followed by recovery, is not that pattern. The Trinity study lineage that produced the 4% rule tested full 30-year sequences; a temporary 4.2% excursion that reverts sits nowhere near the sustained-opening-decade scenarios that actually broke historical portfolios. The reset becomes real damage only if the decline extends, which is precisely the thing to watch rather than the red day itself.
The levers a retiree actually controls
With saving unavailable, the repair tools are spending and liquidity:
- A spending cut. Trim $4,000 (10%) and the rate falls to $36,000 ÷ $950,000 = 3.8%, below where you started. Temporary flexibility is worth several tenths of a point.
- Pre-committed guardrails. The withdrawal guardrails approach cuts spending by a set percentage when the portfolio breaches a floor and restores it on recovery, converting panic into policy.
- A cash buffer. One to two years of spending in cash lets you skip selling depressed shares entirely. The cash buffer debate is honest that this solves part of sequence risk, not all of it, and that cash drag is the standing cost. What it reliably does is convert a market event into a spending decision instead of a realized loss.
What Portfolio Diversification Bought on the Day
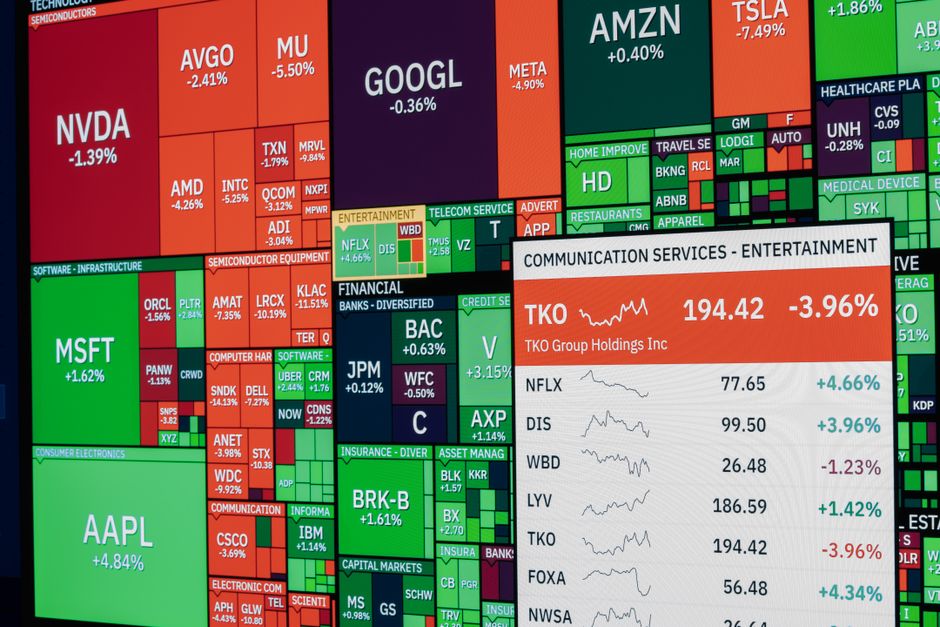
The uncomfortable scoreboard from the November 5 session, when equity correlations converged:
| Sleeve | Same-day move |
|---|---|
| S&P 500 | more than −4% |
| Nasdaq 100 | −5.5% |
| Emerging markets | −6% |
| Semiconductors | more than −11% |
| South Korea | almost −14% |
International equities bought essentially no same-day protection; they fell as much as or more than the US market. Recent IMF analysis reaches the same conclusion about the bond side: stock-bond diversification offers less protection from market selloffs than its long-run record implies. So do bonds protect you when stocks crash? On the day, partially and modestly. A 60/40 with a flat bond sleeve fell about 3% during a 5% equity week, meaning bonds and cash dampened the hit roughly in proportion to allocation. They cushion. They do not offset.
That is the correct frame, because portfolio diversification was never a same-day instrument. Morningstar's 150 year stress test of the 60/40 makes the case on the timescale where it actually operates: shallower total paths and rebalancing opportunities accruing over years, not a hedge that pays out on any given Thursday.
The FIRE-specific question is whether your runway is long enough to collect that payoff. For an accumulator with 10 to 15 years to the number, or a retiree whose critical first decade is the window that matters, the answer is generally yes: that horizon spans multiple market cycles and captures most of the diversification benefit. The case weakens only at short runways, where a locked-in number and five or fewer years of exposure make equity-heavy risk a choice with a real left tail and limited time to harvest the premium.
Your One Evening Drawdown Number
The next selloff should cost you one evening, not one weekend. Five steps:
- Measure the drop on your statement, not the headline. Portfolio before ÷ portfolio after. Your 60/40 fell about 3% in a 5% equity week, and pricing your own event with the index's number is the most common error.
- Compute your multiple: portfolio ÷ annual spending.
- Apply the phase formula:
multiple       = portfolio / annual_spending
damage_x       = drop * multiple
delay_months   = 12 * damage_x / annual_progress_x    (before FI)
new_multiple   = multiple * (1 - drop)                (after FI)
new_wr         = 1 / new_multiple
- Audit your sleeves from the same statement: what did bonds, international, and cash actually do that day? Expect dampening, and stop expecting protection.
- Act on your phase's rule: keep buying (Phase 1), price the delay against one more year (Phase 2), or check guardrails and cash coverage before touching the portfolio (Phase 3).
Know where the arithmetic breaks. Deeper drops scale linearly: a 20% decline at 24x destroys 4.8x, which is two to three years of delay at typical progress rates, a categorically different event. The no-recovery ceiling assumes markets resume normal returns, and a stalled, decade-scale recovery is exactly the sequence risk this site covers elsewhere. Spending drift moves your multiple from the denominator side, so recompute it yearly. And progress assumes a paycheck; for anyone pre-FI, income risk rides along with every market drop.
The November 2026 week will not be the last one. When the next red session arrives, you already have the units, the formulas, and the phase-matched decision. The market will again print a single number, and you will again be the one who sets the price.
Stay in the loop.
Get the latest posts and exclusive content delivered to your inbox.
Join 16 readers. No spam. Unsubscribe in one click, anytime.
About the author
Ethan Carter
Side-Income Writer
Ethan built his first profitable side hustle while working full-time and now runs several income streams alongside his day job. He covers career growth, freelancing, and the earning-more half of the FIRE equation, the part of the formula most people ignore.
Related Posts

S&P 500 Concentration Risk Depends on Your FIRE Date
S&P 500 concentration risk is a sequencing problem for retirees, not accumulators. Sixty years of index churn shows why, plus the bond tent fix.

Small-Cap Value Tilt vs Total Market for FIRE, in FI Months
A small-cap value tilt moves a 50% savings-rate FI date by barely a year, and it deepens early-retirement drawdowns. See the trade-off priced in FI months.
International Stock Allocation for a 50-Year FIRE Portfolio
International stock allocation for FIRE: why the 4% rule is US survivorship bias, and what global 3 to 3.5% withdrawal rates do to your number.